.
No changes.
I indicated that I would look deeply at the end-of-the month signal I just received that moved me to 100% cash and that I would post whether some equity position was required.
We have 2 transfers per month available with the TSP funds. These transfers can be however we choose, but the final transfer must be a sweep to cash (G-Fund). It would be nice to use the available transfer (today before noon EDT) and leave two transfers for October.
While I believe that we are experiencing end-of-the-month and end-of-the quarter window dressing, and that historically, the first few weeks of October are generally positive, there is nothing in my indicators that says we should move into the markets. There is a risk/reward component to this, and when I move against my indicators, it becomes speculation, not investing. If I moved into the equity funds today it would be pure speculation.
I'm sitting 100% in the G-fund, and will end the quarter this way. The next signal to move into the equity funds could be tomorrow (October 1) or it could be much, much later. Your crystal ball is as good as mine. Invest in the markets that are presented to you, not the one that you want.
Regards,
pgd
Tuesday, September 30, 2014

Thursday, September 25, 2014
Moving to 100% G-Fund, Thurs, Sep 25th Update
.
Effective with the close of markets on Thursday, September 25th, my indicators are showing that I need to move to 100% cash.
I am moving all TSP monies to the G-Fund, effective with the close on Friday, 9/26.
I will use the weekend to evaluate if we need to use our 2nd transfer to some form of equity balance -- right now, the answer is cash.
~~~~~~~~~~~~~
As with all my ramblings, you are responsible for your own trading/investing decisions and I am not. Please do your own diligence, and please take ownership for your actions.
Regards,
pgd
Effective with the close of markets on Thursday, September 25th, my indicators are showing that I need to move to 100% cash.
I am moving all TSP monies to the G-Fund, effective with the close on Friday, 9/26.
I will use the weekend to evaluate if we need to use our 2nd transfer to some form of equity balance -- right now, the answer is cash.
~~~~~~~~~~~~~
As with all my ramblings, you are responsible for your own trading/investing decisions and I am not. Please do your own diligence, and please take ownership for your actions.
Regards,
pgd
Thursday, August 14, 2014
Signal Change with 8/13 Close
.
Pushed for time today so this will be brief.
With the close of markets on Wednesday, 8/13, the TSP allocation has signaled a change to LONG.
The signals are weak and mixed, but they are over the threshold and hence, I'm compelled to move long.
Here are the allocations:
Pushed for time today so this will be brief.
With the close of markets on Wednesday, 8/13, the TSP allocation has signaled a change to LONG.
The signals are weak and mixed, but they are over the threshold and hence, I'm compelled to move long.
Here are the allocations:
| Conservative | ||
| AGG | F-Fund | 38% |
| SPY | C-Fund | 27% |
| EFA | I-Fund | 11% |
| VXF | S-Fund | 24% |
| 100% | ||
| Aggressive | ||
| SPY | C-Fund | 44% |
| EFA | I-Fund | 18% |
| VXF | S-Fund | 38% |
| 100% | ||
My horizon in long-term (greater than 10 years) so I am aligning myself with the Aggressive portfolio. Changes made in my TSP account by 12:00 ET will be effective tonight.
~~~~~~~~~~~~~~~~
Obviously, do your own diligence. You are responsible for your investment decisions and I am not. Please take ownership for your actions.
Regards,
pgd
Wednesday, August 6, 2014
8/5/2014 Signals Transition to Cash
.
I'm on the road this week so keeping up on the market has not been as easy as you may think.
With the close of markets over the past few days, and confirmed on 8/5, my indicators are showing that it's time to move to cash and wait for the storm clouds to pass. There are a number of indicators that are bearish, and getting all of these to "line up" is relatively rare except at market transitions.
Of course, your crystal ball is as good as mine.
Since ALL my fail-safe indicators are now bearish, my trading plan has me moving to 100% cash. I have no choice in the matter, as the system has worked for years to keep me out of trouble, especially in the 2008-2009 time frame.
BUT, if you are inclined to consider that we dropped very quickly and are technically oversold and could have a bounce here, a possible good allocation is as follows:
CASH (G-Fund): 53%
S&P500 (C-Fund): 28%
International (I-Fund): 8%
Small-Cap (S-Fund): 11%
I personally am not following these allocations and I will not be tracking the performance of this mixture going forward. I also will not use these numbers to influence future allocations.
Although I have numbers for a non-cash stance I'm not going to provide them -- I think they are too aggressive and simply do not consider that we're in a downward momentum phase of the markets.
~~~~~~~~~~~~
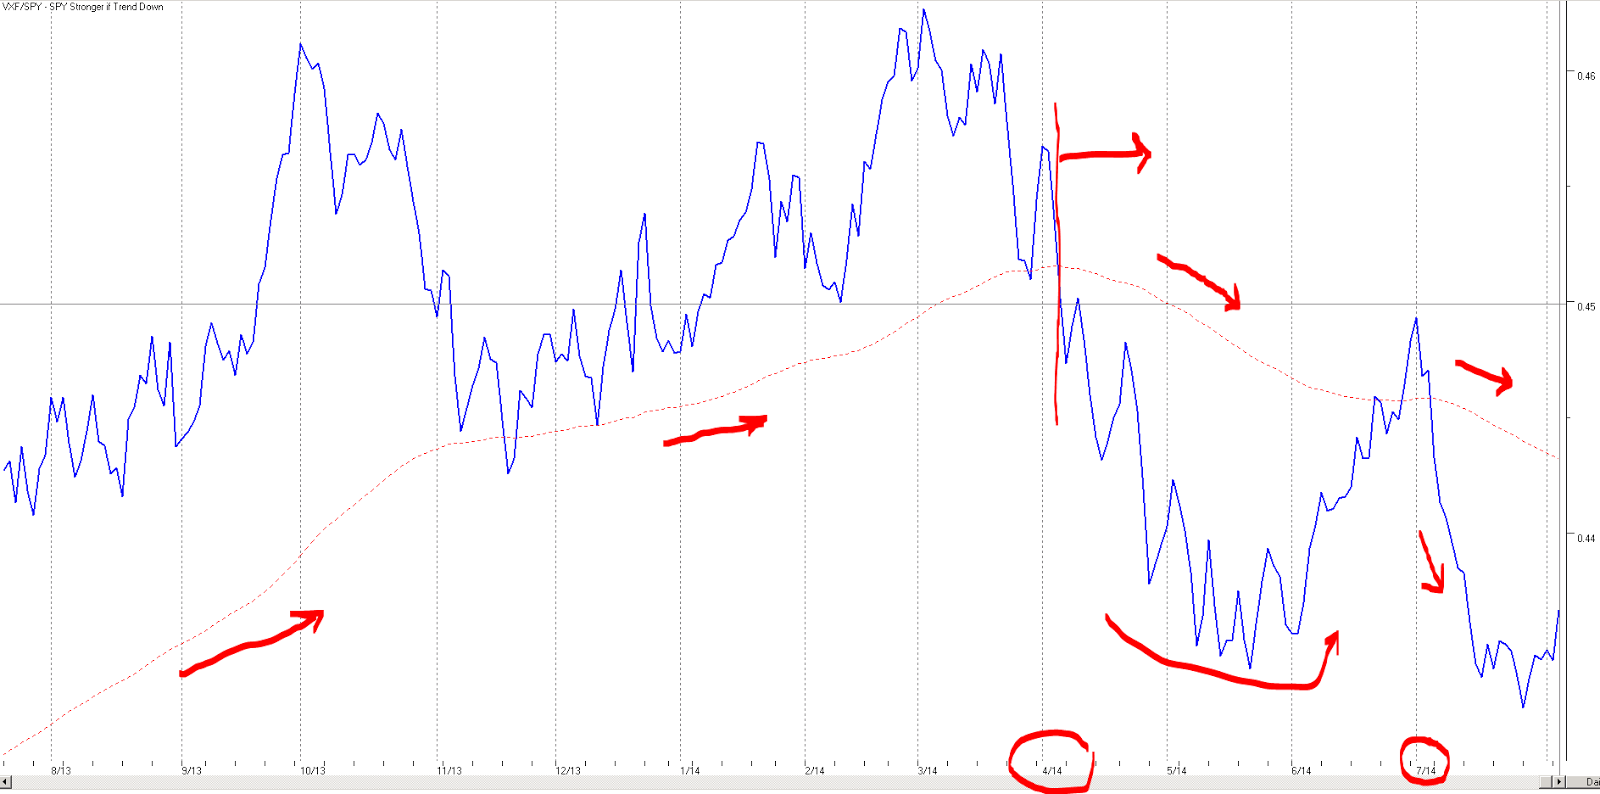
There is no doubt in my mind that we're seeing a transition to safety on a longer-term basis, and this means that we're entering a new phase of the market. This is best illustrated by a relationship that I follow which is the VXF ETF (which represents all the stocks in the market except those in the S&P500) and the SPY (which is the S&P 500 SPDR). Typically, the VXF is considered a "small cap" fund, where the SPY is considered large caps. Indeed, if you look at the individual holdings of each of these ETFs and sort by market cap you can see that the SPY dominates VXF in overall total market cap.
Here's the graph:
Right-click on the image to open in a new tab or window.
The first thing to realize is that up until around the middle of April, the longer-term trend line showed that VXF was outperforming the SPY. There were short-term violations of this concept, but the trend remained intact until mid April. As you can see in the graph above, the trend line has now taken on a downward slope, which means that the SPY is outperforming the VXF on a 65d time frame. There will be short-term violations of this statement too, but in general, money is moving to safety.
The implication for the TSP funds is that going forward we want more allocation to the C-Fund and away from the S-Fund, at least on a medium to long-term basis.
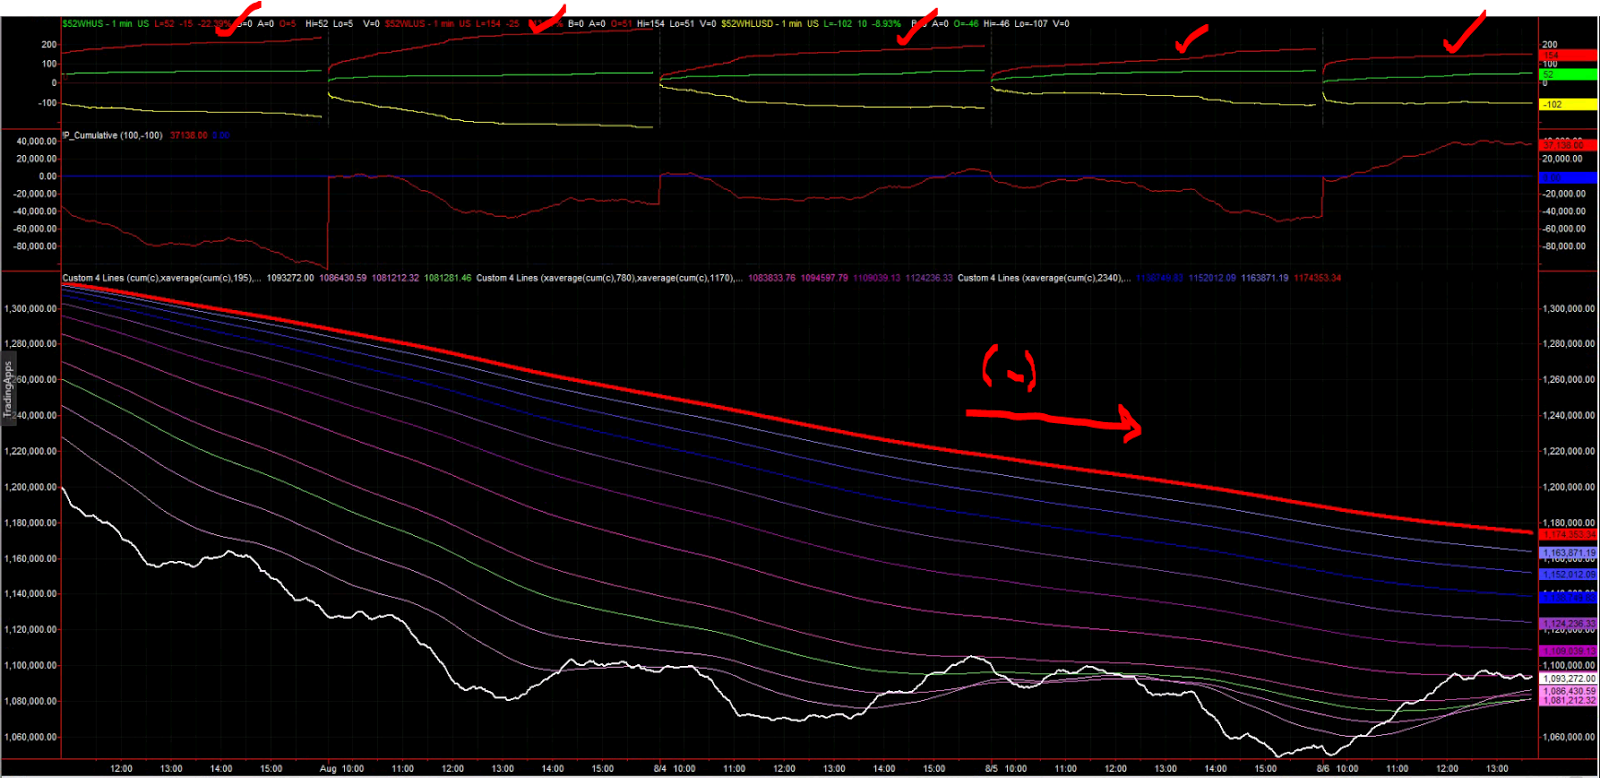
The next indicator that I use, which has not been in this territory for some time, is called a Cumulative Tick Ribbon. Essentially, this is a cumulative count of minute-by-minute transactions on the major exchanges, and it tallies whether all the stocks for a specific "tick" are increasing in price or decreasing in price. When you average these over multiple time frames you get an interesting view:
Right-click on the image to open in a new tab or window.
I'm on the road this week so keeping up on the market has not been as easy as you may think.
With the close of markets over the past few days, and confirmed on 8/5, my indicators are showing that it's time to move to cash and wait for the storm clouds to pass. There are a number of indicators that are bearish, and getting all of these to "line up" is relatively rare except at market transitions.
Of course, your crystal ball is as good as mine.
Since ALL my fail-safe indicators are now bearish, my trading plan has me moving to 100% cash. I have no choice in the matter, as the system has worked for years to keep me out of trouble, especially in the 2008-2009 time frame.
BUT, if you are inclined to consider that we dropped very quickly and are technically oversold and could have a bounce here, a possible good allocation is as follows:
CASH (G-Fund): 53%
S&P500 (C-Fund): 28%
International (I-Fund): 8%
Small-Cap (S-Fund): 11%
I personally am not following these allocations and I will not be tracking the performance of this mixture going forward. I also will not use these numbers to influence future allocations.
Although I have numbers for a non-cash stance I'm not going to provide them -- I think they are too aggressive and simply do not consider that we're in a downward momentum phase of the markets.
~~~~~~~~~~~~
There is no doubt in my mind that we're seeing a transition to safety on a longer-term basis, and this means that we're entering a new phase of the market. This is best illustrated by a relationship that I follow which is the VXF ETF (which represents all the stocks in the market except those in the S&P500) and the SPY (which is the S&P 500 SPDR). Typically, the VXF is considered a "small cap" fund, where the SPY is considered large caps. Indeed, if you look at the individual holdings of each of these ETFs and sort by market cap you can see that the SPY dominates VXF in overall total market cap.
Here's the graph:
Right-click on the image to open in a new tab or window.
The first thing to realize is that up until around the middle of April, the longer-term trend line showed that VXF was outperforming the SPY. There were short-term violations of this concept, but the trend remained intact until mid April. As you can see in the graph above, the trend line has now taken on a downward slope, which means that the SPY is outperforming the VXF on a 65d time frame. There will be short-term violations of this statement too, but in general, money is moving to safety.
The implication for the TSP funds is that going forward we want more allocation to the C-Fund and away from the S-Fund, at least on a medium to long-term basis.
The next indicator that I use, which has not been in this territory for some time, is called a Cumulative Tick Ribbon. Essentially, this is a cumulative count of minute-by-minute transactions on the major exchanges, and it tallies whether all the stocks for a specific "tick" are increasing in price or decreasing in price. When you average these over multiple time frames you get an interesting view:
Right-click on the image to open in a new tab or window.
Ignore the top two panels and simply look at the bottom panel.
The white trace is the real-time, non-averaged value. The red trace is the longest time frame that I average, about 10 trading days. The negative slope of this line is troubling -- it simply tells me that on this time frame that we're down significantly. Further, since the slope is relatively constant for all the days shown, it tells you that we're not out of the woods yet.
Your eye may catch that the real-time, non-averaged value appears to have stabilized into a range. Yes, this is indeed what we are seeing, so perhaps we're at a bottom. We could also be at a pause with a potential to continue downward -- I simply do not know. Best to be prudent and protect gains.
The top panel in the figure above shows the number of NEW LOWS (red), NEW HIGHS (green), and difference between the two (yellow). This is over the past 52 weeks. The figure shows, without any ambiguity, that we are solidly hitting NEW LOWS on a day-over-day basis. Until that green line starts dominating the red line, I'll consider my time on the sidelines well spent.
~
At any rate, do what you will.
Remember, you are responsible for your decisions, and I am not. Please take ownership for your actions.
Regards,
pgd
Sunday, July 27, 2014
Allocation Change -- July 28, 2014
.
With the close of markets on Friday, July 25th, my indicators are showing that a more conservative stance should be taken, at least on a short-term basis.
Here are the new allocations:
G-Fund: 25%
C-Fund: 41%
I-Fund: 22%
S-Fund: 12%
The rationale around this shift has many components, but suffice to say that we're seeing a lack of participation of small cap stocks (S-Fund) and a larger push towards the larger caps (C-Fund).
Since the last allocation change (effective June 30) we've remained relatively flat on performance:
C-Fund, 39% allocation, up +0.40%
I-Fund: 9% allocation, down -0.05%
S-Fund: 52% allocation, down -1.15%
The net of these allocations and performance is a loss of -0.79% in the account.
For the same period the S&P500 was up +1.17%. Of course, hindsight being what it is, it would have been better being 100% in the C-Fund (C-Fund change +1.03%) but my crystal ball is as good as yours.
To show that I eat what I kill, here are the upcoming allocations:



With the close of markets on Friday, July 25th, my indicators are showing that a more conservative stance should be taken, at least on a short-term basis.
Here are the new allocations:
G-Fund: 25%
C-Fund: 41%
I-Fund: 22%
S-Fund: 12%
The rationale around this shift has many components, but suffice to say that we're seeing a lack of participation of small cap stocks (S-Fund) and a larger push towards the larger caps (C-Fund).
Since the last allocation change (effective June 30) we've remained relatively flat on performance:
C-Fund, 39% allocation, up +0.40%
I-Fund: 9% allocation, down -0.05%
S-Fund: 52% allocation, down -1.15%
The net of these allocations and performance is a loss of -0.79% in the account.
For the same period the S&P500 was up +1.17%. Of course, hindsight being what it is, it would have been better being 100% in the C-Fund (C-Fund change +1.03%) but my crystal ball is as good as yours.
To show that I eat what I kill, here are the upcoming allocations:
12 month rolling performance is as follows with less than 1% loss in the account. I've taken a bit more risk in the last several months as I've refined the methods, so I expect gains/losses will increase but the overall risk will remain fairly constant:
~~~~~~~~~~~~~~~
I recently received an email asking how I derive these numbers. The process is relatively straight forward -- I attempt to maximize forward looking gains against minimizing volatility. This all has to be done in context of what "the market" is doing now, and as we all know, this is a moving target.
When people say "the market" the little voice in my head asks "which one?". I say this because different areas of the market act differently at different times. I measure this using something called correlation -- and the result is a matrix as shown below:
Here, ^GSPC is the Yahoo! symbol for the S&P500, and VXF is the Vanguard Extended Market fund, which is an exchange traded fund, much like a mutual fund. The C-Fund and ^GSPC (S&P500) have a "perfect" correlation -- they move together, and the S-Fund and VXF also have a perfect correlation.
In context of "the markets", the real question is what are the expectations of performance given present allocations? Again, remember that performance has to be measured relative to "something".
Let's start with the VXF as the benchmark:
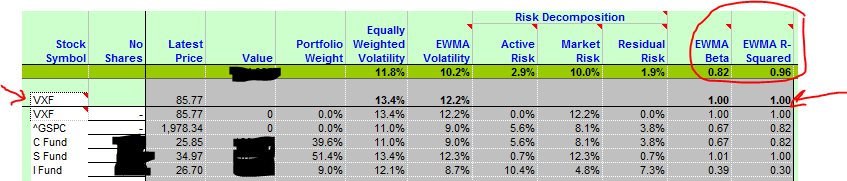
I've circled an area that states "beta" and "R-squared". Beta is the market reference; in this case the VXF is assigned a value of 1.00 and a perfect R-Squared (correlation) of 1.00. For the portfolio allocations over the past month (since June 30th) the expectation was that, relative to the VXF that the portfolio would perform at 82% of the VXF performance, and that 96% of the portfolio performance could be explained by the VXF movement. As it turned out, the VXF fell -1.36% over the last month (not shown but available here) and the portfolio actually only fell -0.79%, so we outperformed the market, relative to the VXF.
What about the "other market", the S&P500? Same process:
Here, ^GSPC is the Yahoo! symbol for the S&P500 market index. Note that the portfolio allocations over the past month are "hotter" than simply investing in the C-Fund (S&P500) -- the beta of 1.09 indicates that the portfolio has the potential to outperform the S&P500 by about 9% of the S&P500 change. This is due to the potential of the VXF (S-Fund) allocation - VXF has (typically) greater performance, but greater volatility too. Adding VXF (S-Fund) adds potential upside/downside, but it also adds risk (volatility).
Te S&P500 went up +1.08% over the last month but the total TSP account fell -0.79% In hindsight this is a "miss", but remember, this is using today's numbers and applying them backwards. What if we used the values available only up to June 27th, which is when I last ran the allocation estimates?
The surprising answer is that the beta estimates and R-Squared values are almost unchanged (less than 1% change). So, sitting back on June 27th, I was looking at 1) how to outperform the S&P500 performance with a high confidence level (expected 9% outperformance of the S&P500 at better than 93% correlation) while minimizing exposure to higher volatility (typically S-Fund, projected allocations said that I would vary at 82% of the S-Fund/VXF variance with a 96% confidence). The higher performance expectation was derived from the overweighting in S-Fund holdings and by adding C- and I-Fund components I was able to minimize portfolio volatility, lowering overall risk.
From a June 27th perspective I *could* have simply put it all in C-Fund and could have been up +1.03% for the period. C-Fund had been underperforming the S-Fund up to this period so that didn't make sense. On the other hand, the S-Fund had been on fire, so overweighting the S-Fund to 100% would have resulted in a loss of -1.36%, so that would have been a terrible miss. Remember, my crystal ball is as good as yours.
It's all a balancing act -- I'm getting better at it, but it's a moving target.
~~~~~~~~~~~~~~~
Remember, you are responsible for your own investment decisions and I am not. Please do your own diligence, and please take ownership for your actions.
My allocation changes will be effective with the close of markets on July 28th.
Regards.
Friday, June 27, 2014
Allocation Change - June 27, 2014
.
It's largely moot whether you do this before noon today or noon Monday. Since we have 2 "free" transfers per month, and we've not used either of them, it's time to change the allocations a bit.
Exposure to Europe and Eurasia has increased risk dramatically, and on a volatility scale, we've moved upward in a dramatic fashion with no rationale for increased gains. Hence, I'm dropping the I-Fund exposure.
For you conservative types, here are my allocations:
C-Fund: 34%
I-Fund: 8%
S-Fund: 46%
F-Fund: 12% (or G-Fund, your choice)
I personally think the bond fund (F-Fund) has inherent long-term risk but for now, it will be "ok".
If you are a bit more aggressive, my allocations are:
C-Fund: 39% (unchanged)
I-Fund: 9%
S-Fund: 52%
It's largely moot whether you do this before noon today or noon Monday. Since we have 2 "free" transfers per month, and we've not used either of them, it's time to change the allocations a bit.
Exposure to Europe and Eurasia has increased risk dramatically, and on a volatility scale, we've moved upward in a dramatic fashion with no rationale for increased gains. Hence, I'm dropping the I-Fund exposure.
For you conservative types, here are my allocations:
C-Fund: 34%
I-Fund: 8%
S-Fund: 46%
F-Fund: 12% (or G-Fund, your choice)
I personally think the bond fund (F-Fund) has inherent long-term risk but for now, it will be "ok".
If you are a bit more aggressive, my allocations are:
C-Fund: 39% (unchanged)
I-Fund: 9%
S-Fund: 52%
I've placed my changes and they will be effective as of the close of markets today.
Since our last signal (May 29th) we have the following changes:
C-Fund: up +1.9%
F-Fund: up +0.02%
I-Fund: up +0.53%
S-Fund: up +3.47%
At the previous allocations, I'm up about +2.1% in the account since the start of the last signal.
~~~~~~~~~~~~~~~
As with all my postings, these are for informational purposes only. You are responsible for your own decisions, and I am not. Please do your own diligence, and please take ownership for your personal actions.
Regards,
pgd
Thursday, May 29, 2014
New Long Signal, May 29, 2014
.
With the close of markets on Thursday, May 29, 2014, my timers have all signaled "long". This means that I am transitioning from the TSP "G Fund", which is essentially a money market, into the equity funds.
If you are conservative you may want to consider a position in the F-Fund, which is a bond fund. The F-Fund is up 1.11% over the past month, due mostly to the weakness of equities, but with the summer months here it could be a slight hedge against the equity markets. Of course, you could leave a position in the G-Fund and lower your risk by that amount.
Representative "Conservative" positioning would be along the lines of:
F-Fund: 12%
C-Fund: 32%
I-Fund: 26%
S-Fund: 30%
Because Kari has a long number of years before she can tap these monies, we're more aggressive. Our allocations for the next leg are:
C-Fund: 39%
I-Fund: 26%
S-Fund: 35%
Note that there is no position in the G-Fund (money market) or F-Fund (bonds). We are fully exposed to the market with this allocation.
The change has been made -- if you make the change before noon EDT on 5/30/2014 it most likely will be made Friday night and will count against the May transfer allotment of 2 transfers per month. This means we are starting June with a clean slate, which is always welcomed.
As always, you are responsible for your investment decisions and I am not. Please do your diligence, and please take ownership for your actions.
Regards,
pgd
With the close of markets on Thursday, May 29, 2014, my timers have all signaled "long". This means that I am transitioning from the TSP "G Fund", which is essentially a money market, into the equity funds.
If you are conservative you may want to consider a position in the F-Fund, which is a bond fund. The F-Fund is up 1.11% over the past month, due mostly to the weakness of equities, but with the summer months here it could be a slight hedge against the equity markets. Of course, you could leave a position in the G-Fund and lower your risk by that amount.
Representative "Conservative" positioning would be along the lines of:
F-Fund: 12%
C-Fund: 32%
I-Fund: 26%
S-Fund: 30%
Because Kari has a long number of years before she can tap these monies, we're more aggressive. Our allocations for the next leg are:
C-Fund: 39%
I-Fund: 26%
S-Fund: 35%
Note that there is no position in the G-Fund (money market) or F-Fund (bonds). We are fully exposed to the market with this allocation.
The change has been made -- if you make the change before noon EDT on 5/30/2014 it most likely will be made Friday night and will count against the May transfer allotment of 2 transfers per month. This means we are starting June with a clean slate, which is always welcomed.
As always, you are responsible for your investment decisions and I am not. Please do your diligence, and please take ownership for your actions.
Regards,
pgd
Subscribe to:
Posts (Atom)